🏠 The late-2026 Brisbane numbers for first home buyers. Brisbane home values are 5.9% higher than a year ago but have been falling since May, down 4.7% over the three months to September 2026 (Cotality). The QLD $30,000 grant for new homes continues past 30 June 2026, with no end date set. Stamp duty is $0 on new builds at any price. And with the cash rate at 4.60% since 30 September 2026, borrowing power is about a third lower than in 2021. Here is the maths.
Maya is 28, a registered nurse in Brisbane earning $89,000. She has $62,000 in savings, enough for a 5% deposit on a home up to $1,000,000, the Brisbane price cap under the federal 5% Deposit Scheme. Her parents in Sydney ask whether she should buy there instead. Cotality's September 2026 index gives part of the answer: over 12 months, Brisbane values rose 5.9% while Sydney fell 7.0% and Melbourne fell 6.2%. But Brisbane has been falling too. It is 5.4% below its May 2026 peak, and in September it fell 1.5%, more than any other capital.
For a first home buyer, the bigger difference between the two cities is the help on offer. Queensland's grant and stamp duty rules give Brisbane buyers more upfront help than most states. Here is what buying in Brisbane looks like in late 2026.
Brisbane vs the Other Capitals — September 2026
Change in dwelling values to 30 September 2026, from the Cotality Home Value Index:
| City | 12 months | 3 months | Median value |
|---|---|---|---|
| Brisbane | +5.9% | −4.7% | $1,048,880 |
| Darwin | +11.9% | +0.5% | $633,431 |
| Perth | +10.1% | −4.7% | $975,022 |
| Hobart | +7.0% | −1.2% | $741,496 |
| Adelaide | +6.5% | −2.7% | $928,560 |
| Canberra | −1.6% | −3.2% | $861,744 |
| Melbourne | −6.2% | −3.4% | $780,550 |
| Sydney | −7.0% | −4.9% | $1,198,596 |
Source: Cotality (formerly CoreLogic) Home Value Index, released 1 October 2026. The median value is Cotality's modelled value of all homes in the city, not a median sale price.
Brisbane's median home is now valued at $1,048,880. That is above the 5% Deposit Scheme's $1,000,000 cap for Brisbane and well above the $750,000 limit for the Queensland grant, so first home buyers using both are shopping well below the middle of the market. Homes are also taking longer to sell: across the capitals, a median of 39 days in September 2026, up from 23 a year earlier.
QLD Stamp Duty for First Home Buyers — The $0 Rule
Queensland's first home rules for transfer duty (stamp duty), in force since 1 May 2025:
- Newly built homes: $0 transfer duty at any price. There is no value cap. A $1.2 million new apartment in South Brisbane attracts $0 transfer duty for an eligible first home buyer.
- Existing (established) homes: $0 up to $700,000, with a smaller concession from $700,001 up to $800,000. From $800,000 the first home concession no longer applies, but the home concession for owner-occupiers still does.
- Vacant land to build a first home: $0 at any price.
For comparison: NSW charges first home buyers no duty up to $800,000 (concession to $1 million). Victoria: none up to $600,000 (concession to $750,000). WA: none up to $600,000 (concession to $800,000) for contracts from 7 May 2026. South Australia matches Queensland on new homes, with no duty at any price, but gives no relief on established homes. The ACT has charged eligible first home buyers no duty at any price since 1 July 2026.
The dollar value: measured against Queensland's general transfer duty rates, as the Queensland Revenue Office does, a $750,000 new build saves $26,775. A $1,000,000 new build saves $38,025, and a $1,200,000 one saves $49,525. An owner-occupier who isn't a first home buyer would pay the home concession rate instead: $19,600 on a $750,000 home.
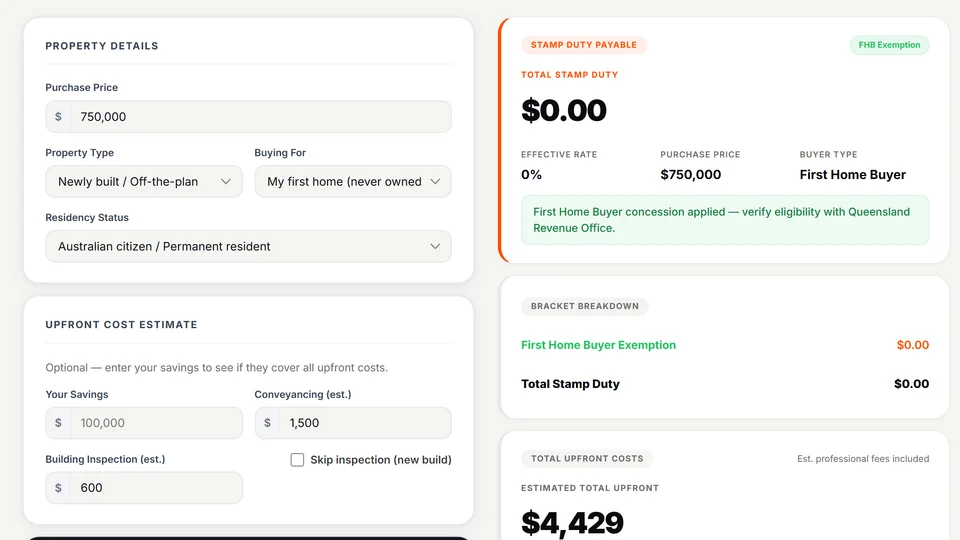
Stack the $30,000 QLD First Home Owner Grant
On top of the stamp duty waiver, the Queensland First Home Owner Grant pays $30,000 to eligible first home buyers who buy or build a new home under $750,000. It was due to fall to $15,000 for contracts signed from 1 July 2026. The Queensland Government kept it at $30,000 instead, and no end date has been set.
Eligibility (basics):
- At least one of you must be an Australian citizen or permanent resident, aged 18 or over
- Neither you nor your spouse can have owned and lived in a home in Australia since 1 July 2000
- The property must be a new home (never lived in or sold as a home, or substantially renovated) valued under $750,000 including land
- You must move in within 1 year and live there for at least 6 continuous months
- The amount goes by the date you sign the contract; settlement and build completion can come later
Stacking with stamp duty and the 5% Deposit Scheme: The federal Australian Government 5% Deposit Scheme (formerly the Home Guarantee Scheme, which includes the First Home Guarantee) lets eligible buyers purchase with a 5% deposit and no LMI, with the government guaranteeing up to 15% of the price. Since 1 October 2025 there are no income caps and no limit on places, and Brisbane's price cap is $1,000,000. A first home buyer buying a $750,000 new build in Brisbane can stack:
| Benefit | Dollar value on $750k new build |
|---|---|
| QLD stamp duty (vs general rates) | $26,775 saved |
| QLD $30k First Home Owner Grant | $30,000 cash |
| 5% Deposit Scheme (LMI avoided on a 5% deposit) | About $22,000 or more |
| Total upfront benefit | About $79,000 or more |
LMI estimates for a home around $750,000 with a 5% deposit run from about $22,000 to more than $30,000, depending on the lender and insurer (Your Property Guide and money.com.au, October 2026). The total uses the lower figure.
What You Can Actually Borrow in 2026
The RBA raised the cash rate to 4.60% on 29 September 2026. It was the fourth rise of 2026 and took the cash rate to its highest level since 2011. Lenders passed it on in full from 8–9 October. For first home buyers, the bigger effect is on borrowing power. Banks test whether you could repay at your loan rate plus 3%. The table below assumes a loan rate of 7.10% (6.85% before the September rise), so the test rate is 10.10%. Lenders advertising lower rates (from 6.29% in October 2026) will usually lend a little more.
Approximate first home buyer borrowing capacity at a 7.10% loan rate (owner-occupier, principal and interest, no other debts, 30-year term):
| Income | Borrowing capacity (October 2026) | Mid-2021 (for context) | Drop |
|---|---|---|---|
| Single, $80,000 | $420k–$465k | ~$680k | −35% |
| Single, $100,000 | $550k–$595k | ~$870k | −34% |
| Single, $120,000 | $665k–$720k | ~$1.05M | −34% |
| Couple, $130k combined | $685k–$755k | ~$1.08M | −33% |
| Couple, $160k combined | $830k–$900k | ~$1.33M | −35% |
Ranges reflect different lender appetites (Big 4 vs second-tier). Assumes 5% deposit, 5% Deposit Scheme, no other personal debt, no dependents. Each further 0.25% rise in your loan rate trims these figures by about 2%. Add HECS/HELP at ~$10k–$25k reduction per $100 of monthly repayment — see how HECS cuts your borrowing capacity. Mid-2021 figures use 0.10% cash rate and 5.25% APRA buffer floor for illustration.
On these figures, a Brisbane couple on $130,000 combined borrows around $685,000–$755,000. With a $62,000–$100,000 deposit, that puts them in the $750,000–$850,000 purchase range. On a new home under $750,000, the $30,000 grant adds to the deposit as cash.
Four Brisbane Areas First Home Buyers Look At
Each area below suits a different budget and type of home. Prices change quickly in a falling market, so check recent sales in the street rather than last year's suburb median.
- Chermside / Aspley (north Brisbane): an established centre with Westfield Chermside and The Prince Charles Hospital. Mostly houses and townhouses. Check bus links to the city and the flood map before you buy.
- Carindale / Mount Gravatt (south-east): established middle-ring suburbs with strong demand for school catchments (see what a school zone premium costs against private school fees). Look for new townhouse projects priced under the $750,000 grant limit.
- Coorparoo / Greenslopes (inner south): close to the city, with a lot of new apartment supply. A new apartment attracts $0 stamp duty at any price for a first home buyer, and the grant if it's under $750,000. Check body corporate fees before you sign.
- Springwood / Slacks Creek (Logan): among the more affordable areas within reach of Brisbane, with house-and-land packages that can fall under the grant limit.
This is not financial advice — every suburb requires its own due diligence on flood overlay, body corporate fees, school zones, future development supply, and infrastructure. Speak to a buyer's agent or local conveyancer before signing anything.
The Decision Framework — Sydney vs Brisbane for an $89,000 Single Earner
Maya (Brisbane, $89,000, $62,000 deposit) compared with a Sydney buyer on the same income and deposit, both buying their first home now:
| Variable | Sydney first home buyer | Brisbane first home buyer |
|---|---|---|
| Borrowing capacity (7.10% loan rate) | ~$480k | ~$480k |
| Stamp duty on a new home | $0 up to $800,000 | $0 at any price |
| Stamp duty on an established home | $0 up to $800,000 | $0 up to $700,000 |
| State grant (new home) | $10,000 (new home up to $600,000, or $750,000 for house and land) | $30,000 (under $750,000) |
| Median dwelling value (Sep 2026) | $1,198,596 | $1,048,880 |
| Value change, 12 months to Sep 2026 | −7.0% | +5.9% |
| Value change, 3 months to Sep 2026 | −4.9% | −4.7% |
| Summary | Smaller grant; prices falling over the year | Bigger grant and duty savings; prices falling since May after a strong year |
The clearest difference is the upfront help. On price direction, both cities fell over the three months to September 2026, so neither buyer can count on the next year looking like the last.
Before You Sign: A 5-Day Action Plan
- Day 1 (today): Ask at least 3 lenders for pre-approval to confirm your real borrowing capacity at current rates.
- Day 2: Check your eligibility for the 5% Deposit Scheme at firsthomebuyers.gov.au and apply through a participating lender. Once pre-approved, you have 90 days to find a home and sign a contract.
- Days 3–4: Inspect 5–10 properties matching your top-2 suburb targets. If targeting new builds, confirm the total price including land is under $750,000, the grant limit.
- Day 5: Make an offer. Ask your conveyancer to confirm grant eligibility before you sign.
Settlement can occur weeks later, and a new home can be finished well after you sign. For the grant, the contract date is what counts. Talk to a Brisbane-based buyer's agent or conveyancer this week if you are genuinely ready to move.
Frequently Asked Questions
Is now a good time to buy a first home in Brisbane?
There's no single right time, but here is where things stand. Brisbane home values were 5.9% higher than a year earlier in September 2026, but they have fallen since May and dropped 4.7% over the three months to September (Cotality). First home buyers in Brisbane get three breaks: no stamp duty on a new home at any price, a $30,000 grant for new homes under $750,000 (with no end date set), and the federal 5% Deposit Scheme. The catch is borrowing: with the cash rate at 4.60% since 30 September 2026, buyers can borrow about a third less than in mid-2021.
How much stamp duty do first home buyers pay in Brisbane in 2026?
None on a new home or vacant land, whatever the price, for contracts signed from 1 May 2025. On an existing home, first home buyers pay no stamp duty up to $700,000. Above that the discount shrinks, and it's gone at $800,000. If you've owned a home before but are buying one to live in, Queensland's home concession charges 1% on the first $350,000, a saving of up to $7,175.
When does the $30,000 Queensland First Home Owner Grant expire?
It has no end date. The grant was due to drop to $15,000 for contracts signed from 1 July 2026, but the Queensland Government kept it at $30,000 and hasn't set an end date. It applies to new homes under $750,000, including the land. What counts is the date you sign the contract, not the settlement or build date. Source: Queensland Government and Queensland Revenue Office, checked 19 October 2026.
What can a $100,000 income borrow in Brisbane in 2026?
Roughly $550,000 to $595,000 for a single person on $100,000 with no other debts, and about $830,000 to $900,000 for a couple earning $160,000 between them. These figures assume a 7.10% loan rate (6.85% plus the September 2026 rise), which banks test at 10.10%, the rate plus 3%. Some lenders advertise lower rates and will lend a little more. Borrowing power is about a third lower than in mid-2021, when the cash rate was 0.10%. The exact amount varies by lender.
Should I buy a new build or an established home in Brisbane as a first home buyer?
On tax and grants alone, a new build comes out ahead in Brisbane: no stamp duty at any price, and the $30,000 grant if it costs under $750,000. An established home has no stamp duty only up to $700,000 (phasing out by $800,000) and no grant. But it often comes with a bigger block, a settled suburb and lower strata fees than a new apartment. Location, lifestyle and how easily the home will sell later matter as much as the tax side.